Qualcomm Bets On Auto, IoT And Data Center Growth
Is down 21% in three months, but the company’s auto and data center push is starting to offset weaker handset revenue. Management says the first revenue from…
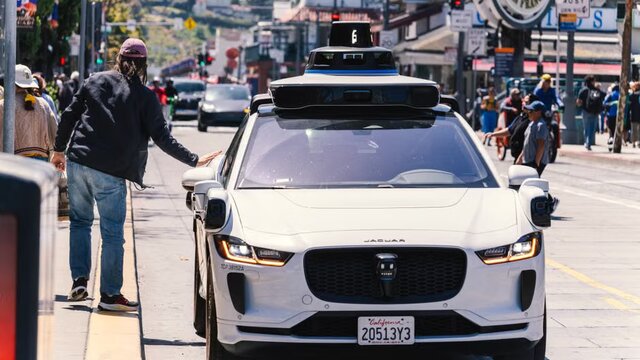
NEW YORK — Qualcomm stock has fallen 21% over the trailing three months and now trades about 36% below its 52-week high, but investors are watching a different part of the business for the next move. The company’s non-handset revenue is inflecting fast enough that management expects it to replace revenue Apple is taking away, with the first proof due in the December quarter.
That matters because Qualcomm’s handset business is still under pressure from memory costs and a faster-than-planned unwind in its Apple relationship. The stock’s next leg, if it comes, will likely depend on whether automotive, Internet of Things and data center orders can scale quickly enough to take over the load.
Auto is already showing the shift
Automotive is where Qualcomm’s transition is most visible. Revenue rose from $1.3 billion in fiscal Q2 2026, up 38% year over year, to a quarterly record $1.6 billion in fiscal Q3 2026, up 61%. Management says the annualized exit run rate targeted for fiscal 2026 has moved from above $6 billion in April to approximately $7 billion.
Demand is being helped by rising compute content per vehicle. Qualcomm said the fifth-generation Snapdragon digital chassis begins ramping in September, and BMW has picked Qualcomm as lead compute silicon provider for its next-generation ADAS and digital cockpit. Those are not small signs. They point to a business that is no longer just a side bet.
Two hyperscalers, two purchase orders
The bigger story is data center computing. In April, Qualcomm was talking about one custom silicon engagement with a leading hyperscaler. Now management says there are two, both global-scale hyperscalers, with purchase orders in hand, wafers running and revenue starting in the December quarter.
That is a meaningful shift. It gives the company a visible revenue line in a business that could matter far more than early-stage pilot talk. But the concentration is real, too. Qualcomm is now relying on a small number of large customers to prove the case.
Handsets are still the drag
The handset side remains the weak spot. Qualcomm’s handset revenue was $5.1 billion in fiscal Q3 2026, and its share of the coming iPhone launch will be materially below its prior 20% estimate. Qualcomm also expects its modem share in the upcoming iPhone launch to be materially below that same assumption.
Apple’s move is part of the pressure. Qualcomm said Apple product revenues are expected to fall about 50% sequentially from the September to December 2026 quarters, and fiscal 2027 Apple product revenues are expected to come in below the prior outlook of slightly more than $2 billion. Apple has introduced the C1, its first internally designed cellular modem, in the iPhone 16e.
Qualcomm says its fiscal 2027 non-handset growth should replace fiscal 2026 Apple product revenues. The question is speed. The handset business is shrinking now, while the replacement businesses are still building scale.
Why the market is paying attention
For investors, the key issue is not whether Qualcomm can grow outside smartphones. It already is. The issue is whether that growth can arrive fast enough to offset softer mobile economics and margin pressure.
Qualcomm CDMA Technologies’ combined automotive and Internet of Things revenues grew 28% year over year in the fiscal third quarter of 2026. Management expects non-handset revenue growth to accelerate from 24% in fiscal 2026 to more than 60% in fiscal 2027, with non-handsets expected to represent more than half of Qualcomm CDMA Technologies revenues in fiscal 2027.
Margins are also under strain. Qualcomm CDMA Technologies’ earnings-before-taxes margin fell to 26% in the fiscal third quarter from 30% a year earlier, and the company guides for a 23%-25% margin in the fiscal fourth quarter as higher product costs and the business mix weigh on results. Stellantis expanded its multi-year technology collaboration with Qualcomm in May 2026 across cockpit, connectivity and driver-assistance systems, another sign the auto pipeline is broadening.
The next hard checkpoint comes in the December quarter, when Qualcomm says revenue from its two hyperscaler customers is set to begin.