Macquarie Bank Expected to Pay $14M Penalty Over Savings Rate Promotions
Macquarie Bank is expected to pay a $14m civil penalty after admitting its “welcome rate” promotions could mislead savings customers about bonus interest. The Australian Securities and Investments Commission says the bank’s systems failed to identify the risk that customers would misunderstand how the rate worked.
Macquarie Bank is expected to pay a $14m civil penalty in Australia after admitting its savings “welcome rate” promotions could mislead customers about bonus interest.
The bank will not contest the proceedings, and the penalty is subject to court proceedings. The Australian Securities and Investments Commission said Macquarie’s systems and controls did not adequately identify the risk of customer confusion.
How the rate promotion worked
Macquarie described its savings offer as a “welcome variable rate” or “bonus” in promotional material in 2022. The wording could lead customers to think the rate was added to the standard variable rate, the regulator alleged in NSW Supreme Court proceedings.
As interest rates rose that year, the difference between the welcome rate and the standard rate narrowed. When the standard rate moved above it, customers received only the standard rate, without an additional bonus, according to the regulator’s case.
Macquarie said it would admit in court that it had failed to provide financial services “efficiently, honestly and fairly.” A spokesperson said the bank “will not contest the proceeding and is expected to pay a $14m civil penalty.”
Regulator urges customers to check conditions
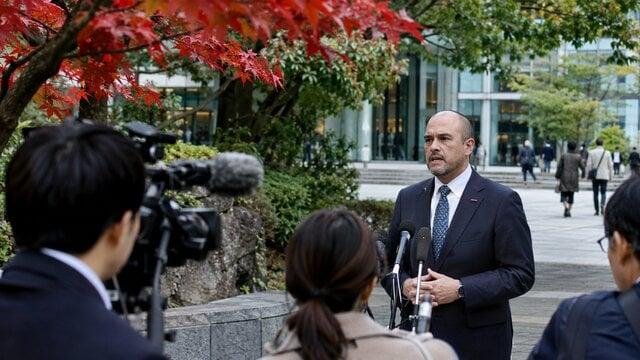
ASIC Commissioner Alan Kirkland said customers should not need to inspect every transaction to confirm their bank had paid the right interest. “Banks must get the basics right, which includes having systems and processes that deliver on the promises they make to customers,” he said.
Kirkland said the problem went beyond unclear promotional language. Macquarie’s controls, he said, were not strong enough to detect that customers might misunderstand how the welcome rate worked.
He also warned that a bank’s highest advertised rate may apply only for a limited period or depend on customers meeting specific conditions. Those requirements can include making a monthly deposit, increasing an account balance or avoiding withdrawals.
A 2023 study by the competition regulator found that 71% of bonus-interest accounts did not receive the bonus rate in a given month because customers failed to meet conditions.
RMIT finance professor Angel Zhong said banks’ promotional offers for savings products “get louder” when interest rates move. “That is exactly when clear, honest rate disclosure matters most, because small differences in wording can steer big decisions,” Zhong said.