Nvidia and Intel Shares Fall After Earnings and Outlook
Nvidia shares fell after a strong quarterly report, while Intel’s weak outlook has weighed on its stock. An investor known as The Curious Analyst rates Nvidia a Strong Buy and Intel a Hold, citing different prospects for profitability and growth.
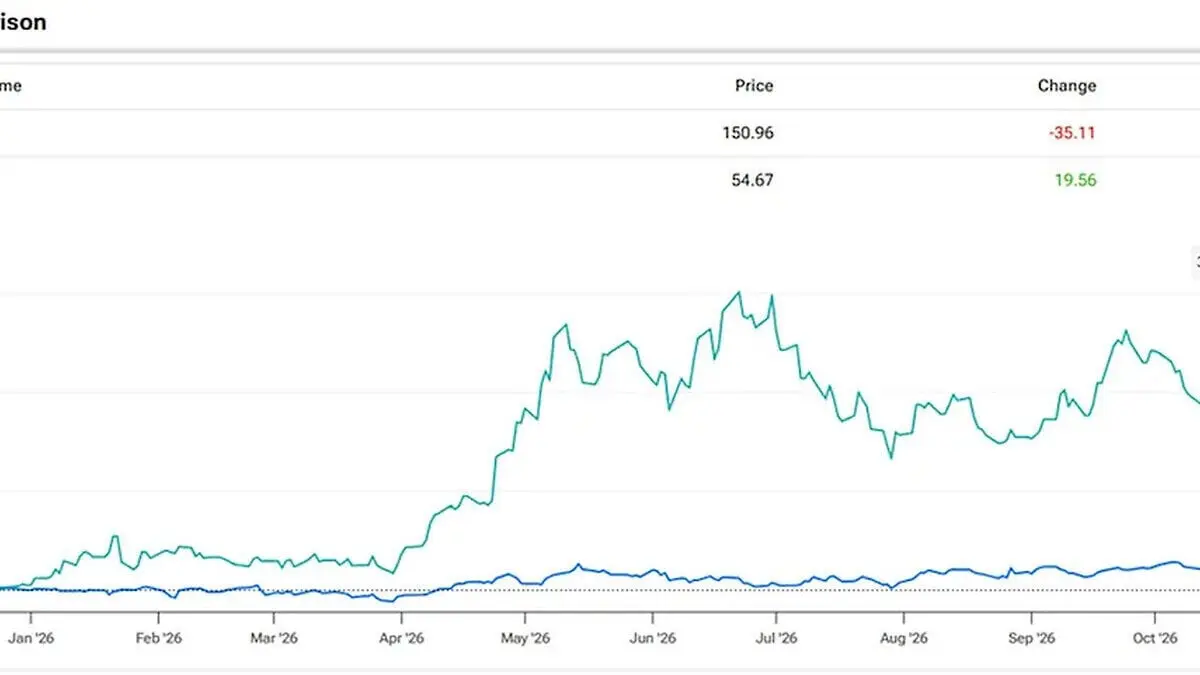
Nvidia and Intel shares have fallen after their latest financial updates, with Nvidia declining after earnings and Intel sliding following a weak outlook. Investor The Curious Analyst sees different prospects for the two chipmakers.
The investor rates Nvidia a Strong Buy and Intel a Hold. Nvidia’s shares fell after its third-quarter earnings report, its first since Jensen Huang resigned as chief executive.
Intel lost more than a quarter of its value after its fourth-quarter revenue forecast fell short of analysts’ expectations. Its shares are about 60% below their June peak.
Nvidia Revenue Doubles as Shares Fall
Nvidia’s third-quarter revenue more than doubled from a year earlier to $115.8 billion. Interim Chief Executive Colette Kress raised the company’s fiscal 2028 growth forecast to 75% from 70%.
On the earnings call, board chair Harvey Jones said the board did not intend to reinstate Huang. Huang had said hours earlier that he would be honored to return.
Nvidia shares are near their lowest level since around June 2025. The Curious Analyst said the leadership uncertainty was already reflected in the share price.
The investor pointed to a milder market reaction to the board’s decision than to Huang’s departure, interpreting it as a sign of confidence in Kress.
Nvidia’s Vera Rubin products added nearly $20 billion in revenue from the previous quarter. The investor expects growth to continue as Vera Rubin expands alongside Blackwell Ultra.
The Curious Analyst also expects Nvidia to use its remaining share buyback authorization of about $227 billion by the end of fiscal 2028. Management has said it plans to do so.
The investor identified a slowdown in artificial intelligence spending and a reluctance to value Nvidia as highly without Huang as risks.
Intel Faces Profitability Questions
Intel’s fourth-quarter revenue guidance had a midpoint of $15.5 billion, below the roughly $17 billion analysts expected. The company’s trailing 12-month net margin is about -20%.
The Curious Analyst assumes revenue will grow about 9% next year and net margin will recover to 6%. That model produces a 2027 earnings estimate of $0.78 per share, below the Wall Street consensus of $1.79.
The investor also cited the risk of further dilution after Intel sold more than $20 billion in stock in August. Other concerns include margins falling again and investors becoming less willing to pay the current earnings multiple.
Intel faced a shareholder lawsuit, while a filing showed Nvidia had sold about a quarter of its Intel stake.
The Curious Analyst wants to see Intel’s fourth-quarter results and its 2027 outlook before deciding whether to change the Hold rating.
 Take the quizWhat Kind of Holiday Spender Are You? Take the Black Friday QuizStart →





 Lifestyle · Food & HealthWhat Is Raynaud’s Syndrome? Why Fingers Turn White in the Cold
 Lifestyle · Food & Health4 Ways Walking After Meals Helps Your Body, Doctors Say
 Lifestyle · Food & Health4 Reasons to Eat Oatmeal, According to Nutrition Experts
 Lifestyle7 Signs Your Social Battery Is Running Low (and Why You Keep Cancelling Plans)