FDIC Insurance for Business Accounts: The $250,000 Limit
See how business structure, account ownership and separate banks affect FDIC coverage for operating cash.
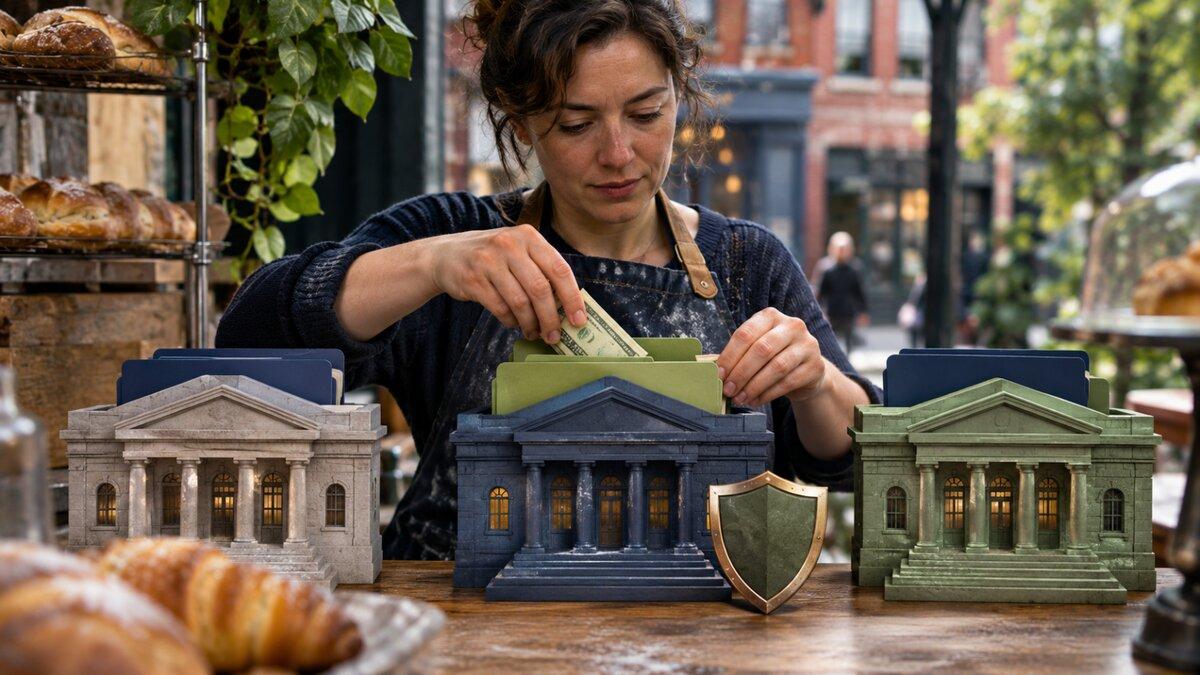
FDIC insurance generally covers a qualifying business’s deposits up to $250,000 at each FDIC-insured bank, combining its accounts rather than protecting each separately. For owners managing payroll and supplier payments, understanding FDIC insurance for business accounts starts with identifying the legal owner, the bank holding the money and the applicable deposit insurance coverage.
- A qualifying corporation or partnership receives coverage separately from its owners’ personal deposits.
- A sole proprietor’s business deposits combine with the owner’s other single-ownership deposits at the same bank.
- Additional accounts, account purposes or authorized signers do not multiply a company’s coverage.
- Separately chartered, insured banks provide separate coverage; branches of one bank do not.
Business ownership determines which deposits combine
The FDIC’s business-account guidance places corporations, partnerships and unincorporated associations in an ownership category separate from their owners’ personal accounts. The organization must conduct an independent activity: it must operate primarily for a purpose other than increasing deposit insurance.
For a qualifying company, accounts earmarked for payroll, taxes and operating expenses are added together at the same bank. Having different purposes or more people authorized to sign does not create additional protection.
A sole proprietorship receives different treatment. Its deposits belong to the individual owner for insurance purposes and combine with that person’s other deposits in the single-account category at the same bank. A separate business account can help organize finances without establishing separate insurance coverage.
The distinction matters before choosing business bank accounts. Account ownership determines how balances combine; product names describe the services being purchased. The FDIC’s glossary explicitly distinguishes an account’s ownership category from its deposit type.
| Business structure or arrangement | Insurance treatment | Applicable USD limit | Main benefit or limitation | Relevant user |
|---|---|---|---|---|
| Sole proprietorship | Combines with owner’s other single accounts at the same bank | $250,000 combined | Business label creates no separate allowance | Individual business owner |
| Qualifying corporation | Company deposits combine at each bank | $250,000 per company, per bank | Separate from owners’ personal deposits | Incorporated business |
| Qualifying partnership | Partnership deposits combine at each bank | $250,000 per partnership, per bank | Partners and signers do not multiply coverage | Partnership finance team |
| Same company using separately chartered, insured banks | Deposits assessed separately at each bank | $250,000 at each bank | Additional banking relationships require separate verification | Business spreading operating cash |
These are coverage limits, not account prices. No particular bank product is being priced or endorsed here.
Separate banks matter more than separate accounts
Under 12 CFR Part 330, deposits at separately chartered and insured institutions receive separate treatment even when those banks share a holding company. Deposits at different branches of the same institution combine.
The practical question for treasury cash management is therefore which legal bank holds each balance. A different branch address does not establish a separate insurance allowance. Before counting another banking relationship as additional protection, verify the institution’s identity and insured status.
The FDIC directs depositors to BankFind to check whether an institution is insured. Its Electronic Deposit Insurance Estimator, EDIE, can then assess a group of accounts on a per-bank basis and produce a report showing covered and excess amounts. The result depends on entering eligible deposits and the correct ownership information.
Records also matter. The regulation generally presumes ownership follows the insured bank’s deposit account records. Clear, unambiguous ownership records can bind the depositor. A business should therefore ask the bank to confirm the account owner and correct inconsistencies before relying on a coverage calculation.
The Small Business Administration’s banking guidance lists formation documents, ownership agreements, a business license and an EIN—or a Social Security number for a sole proprietor—among documents banks commonly request. Those opening documents support identification; the insurance analysis still depends on ownership and applicable rules.
Keep financing decisions separate. Our explanation of SOFR versus prime for business financing addresses borrowing costs, while this coverage check concerns cash already deposited.
Investments and fintech access carry different risks
Checking accounts, savings accounts, money market deposit accounts and certificates of deposit are deposit products addressed by EDIE. The FDIC’s glossary explains that a money market deposit account is a deposit type; its coverage depends on ownership and other deposits in that category at the bank.
A money market mutual fund is an investment. EDIE expressly excludes mutual funds, stocks, bonds, annuities, crypto assets and other investments, including those bought through an insured bank. Buying a product from a bank does not by itself establish deposit protection.
For fintech services, identify both the customer-facing provider and the bank receiving deposits. A joint banking-agency statement hosted by the Federal Reserve warns that insurance does not protect against losses from a nonbank third party’s failure. Pass-through coverage requires applicable conditions to be satisfied.
The agencies also identify record-access problems as a potential cause of delays in customers accessing deposits. For business cash protection, ask who maintains ownership records, how balances can be reconciled and what happens if the provider stops operating. An insurance statement alone does not answer those operational questions.
Credit unions use a different federal system. The NCUA’s share-insurance FAQ identifies corporation, partnership and unincorporated-association accounts among its ownership categories. It also confirms that splitting money among products within one category does not increase coverage. Verify the credit union’s federal insurance and applicable business-account treatment rather than describing its accounts as FDIC-insured.
Match cash arrangements to operating needs
For a sole proprietor, begin by reviewing personal single-ownership deposits alongside business cash at the same bank. For a corporation or partnership, inventory every company deposit there, including accounts maintained for different operating purposes.
If balances approach the applicable limit, evaluate separately chartered, insured institutions and document the allocation. Use EDIE to check the proposed arrangement. Review it again when balances, ownership or banking relationships change.
Then assess service costs. The SBA recommends comparing transaction charges, minimum-balance fees, termination fees and other account features. Our comparison of business account fees provides a separate framework for evaluating services; it does not establish insurance eligibility.
The business decision is to match verified coverage with dependable access and acceptable fees. A finance team should be able to identify who owns its cash, which institution holds it, what records support that ownership and which balances exceed protection before relying on an account for payroll.
- FDIC business-account and ownership guidance.
- FDIC deposit-insurance glossary.
- FDIC EDIE coverage estimator and product exclusions.
- Official 2026 edition of 12 CFR Part 330.
- SBA business-launch guidance, including business banking.
- Federal Reserve: joint statement on third-party deposit arrangements.
- NCUA share-insurance FAQ.
 Take the quizWhat Kind of Holiday Spender Are You? Take the Black Friday QuizStart →
- 1I’m A Celebrity 2026 Line-Up: Rooney Leads 11 Stars Into Jungle

- 2Mavericks Surfers Race to California for Waves Near 50 Feet
- 3NYC Medical Examiner Has Not Determined Cause of Death of Beau Rose Jessup
- 4Mountaineer Finds Ice Age Cave Bear Graveyard in the Dolomites
- 5Rugby League World Cup Final 2026: Kick-Off Times and How to Watch Kangaroos v New Zealand
 Lifestyle7 Signs Your Social Battery Is Running Low (and Why You Keep Cancelling Plans)
 Lifestyle · Food & HealthThanksgiving Food Safety: How Long Leftovers Last and the Safe Turkey Temperature
 Lifestyle7 Quiet Habits of Emotionally Intelligent People, According to Psychologists
 LifestylePeople Who Don’t Like Celebrating Their Birthday Often Share These 7 Traits