FedNow vs FedACH: 2026 Fees and Faster-Payment Costs
Compare official 2026 FedNow and FedACH network fees, temporary discounts and settlement trade-offs—and what businesses should ask their banks.
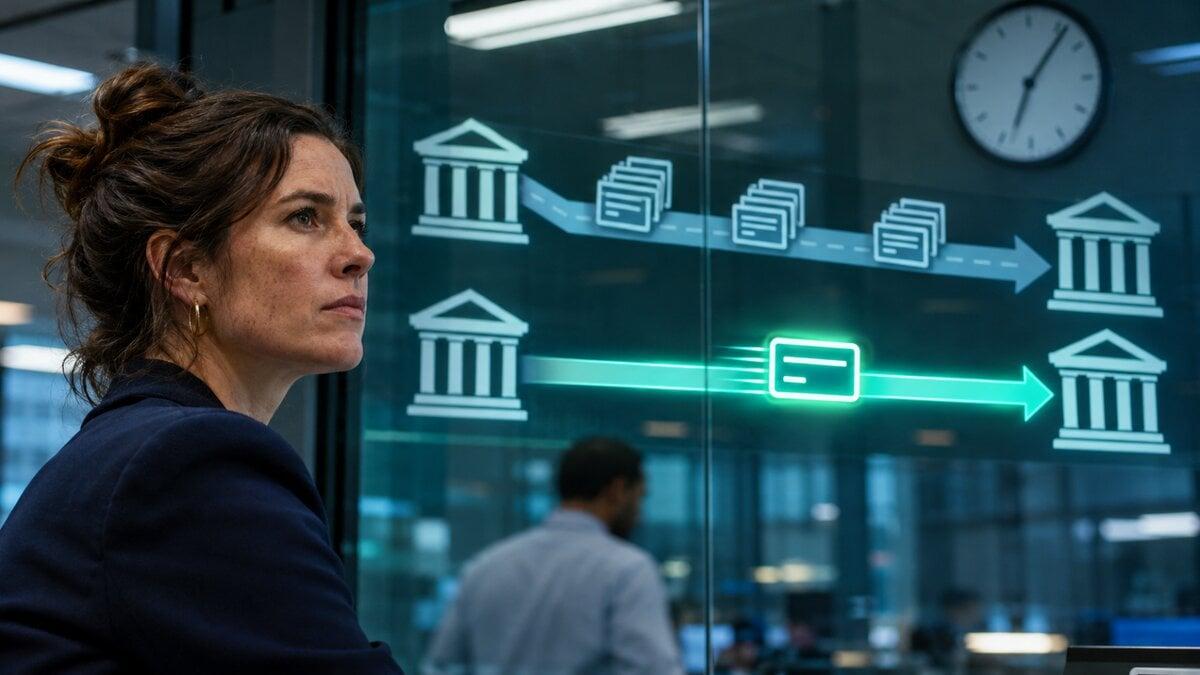
FedACH has the lower standard origination fee, while FedNow offers immediate payments around the clock; temporary discounts complicate the comparison. For buyers assessing FedNow vs ACH fees 2026, the commercial question is how instant payment infrastructure changes delivery, funding and operating costs—not whether a published network charge equals their bank’s price.
Key takeaways
- FedACH’s base origination charge is $0.0035 per item; FedNow’s customer credit-transfer origination charge is $0.045 before discounts.
- FedNow discounts its participation fee and up to 2,500 customer credit transfers monthly in 2026.
- Same Day ACH carries additional charges and settles on banking days; it is not equivalent to continuous instant settlement.
- These are institutional network fees. Business customers need separate bank or payment-provider quotes.
Data checked: November 16, 2026. Jurisdiction: United States. All prices are USD; this comparison uses 2026 schedules.
Official Network Fees and What They Actually Buy
The Federal Reserve’s pricing announcement explicitly concerns services supplied to banks and credit unions, effective January 1, 2026. It does not establish a universal business-customer tariff. Treating the figures below as the price of a commercial payment account would confuse infrastructure charges with a finished banking service.
The table compares published sending-side charges for customer payments. Recommendations in its final column are editorial assessments, not provider guarantees.
| Service or configuration | Published sending charge | Delivery characteristic | Best-fit business use |
|---|---|---|---|
| FedACH standard origination | $0.0035/item base | Scheduled ACH processing | Predictable supplier payments |
| FedACH Same Day origination | Base + $0.0010 surcharge + $0.052 Same Day Entry Fee | Same banking day, subject to eligibility and deadlines | Deadline-driven weekday payments |
| FedNow customer credit transfer | $0.045/item before discounts | Instant, around the clock | Urgent disbursements |
| FedNow discounted credit transfers | $0.045 origination charge offset for up to 2,500/month in 2026 | Same instant service | Institutions assessing initial volumes |
FedACH also lists a $55 minimum monthly forward-origination charge and an $80 monthly participation fee per routing number, subject to its conditions. FedNow’s $25 monthly participation fee per routing number is discounted to zero in 2026. Neither table row represents a complete institutional invoice.
For commercial buyers, request separate quotes for account access, implementation, payment submission and exceptions. Ask which charges are fixed and which increase with volume. Also establish whether promotional savings reach your account and what happens when they expire.
Keep this procurement exercise separate from merchant acceptance. Our Stripe vs PayPal vs Square: 2026 Online Payment Fees comparison addresses another layer of payment purchasing; its prices should not be substituted for interbank network fees.
Settlement Timing Changes the Operational Decision
The FedNow service description says participating financial institutions can provide instant payments every day of the year, with recipients able to access funds immediately. For treasury teams, that makes the timing of usable funds a central purchasing criterion.
ACH supports both credits and debits. Nacha’s fact sheet identifies scheduled payroll, recurring bills and business payments between known counterparties as suitable uses. It also explains that ACH does not currently settle on weekends or federal holidays. Same Day ACH can settle within hours, but it remains distinct from an always-available instant service.
Payment size matters too. Nacha lists the current Same Day ACH ceiling as $1 million per payment. Its approved increase to $10 million takes effect September 17, 2027. A buyer planning a 2026 implementation should not treat that future capacity as already available.
The Federal Reserve’s 2026 service announcement reports FedNow’s network limit increase to $10 million. Buyers should still obtain written confirmation of their own bank’s permitted payment size and available services rather than building a workflow around the network ceiling alone.
FedNow is credit-push only, and its transfers are irrevocable, according to a Federal Reserve Bank of Philadelphia explanation. Procurement should therefore examine beneficiary checks, approval controls and recovery procedures before increasing sending access. Do not assume an instant payment can simply be cancelled after settlement.
For a real-time payments platform, require a demonstration that distinguishes accepted, settled, rejected and returned payments. Ask how each status reaches accounting staff and how the provider handles uncertain outcomes. A faster transfer delivers less operational value if the finance team cannot determine whether it completed.
Choose by Payment Deadline and Total Business Cost
Choose standard ACH for predictable payments when the required delivery date permits scheduling. Prioritize ACH automation software that supports approval workflows, reconciliation and exception handling. Request evidence that the product fits your actual file formats and accounting processes before comparing subscription prices.
Choose Same Day ACH when a banking-day deadline requires acceleration and the payment meets current eligibility requirements. Using the undiscounted base figures above, the listed sending components total $0.0565 per eligible item: $0.0035 plus $0.0010 plus $0.052. This calculation excludes other charges and is not a customer quote. It also shows why instant payments should not automatically be assumed to have the higher transaction charge.
Choose FedNow when immediate delivery outside ordinary settlement days has a defined business purpose, such as an urgent supplier payment. Before contracting, verify recipient availability, sending permissions, funding arrangements and support coverage with the provider. Include the cost of operating the process whenever your business intends to use it.
For a company comparing bank payment processing fees, build a cost model from its own payment volumes and quoted terms. Include implementation, recurring charges, transaction fees, exception work and funding costs. Customer-specific pricing is not disclosed in the network schedules reviewed here; obtain it directly rather than estimating a bank markup.
Where borrowing finances disbursements, evaluate the timing separately using the approach in SOFR vs Prime: What a $100,000 Business Credit Line Costs. Earlier availability does not establish a financing saving without the business’s actual borrowing rate and cash schedule.
The strongest purchasing decision assigns each payment a required delivery time, then selects a service capable of meeting it at an acceptable quoted cost. Network fees provide a useful benchmark; recipient access, controls and the business’s operating requirements determine whether faster delivery is worth buying.
 Take the quizWhat Kind of Holiday Spender Are You? Take the Black Friday QuizStart →
- 1I’m A Celebrity 2026 Line-Up: Rooney Leads 11 Stars Into Jungle

- 2Mavericks Surfers Race to California for Waves Near 50 Feet
- 3NYC Medical Examiner Has Not Determined Cause of Death of Beau Rose Jessup
- 4Mountaineer Finds Ice Age Cave Bear Graveyard in the Dolomites
- 5Rugby League World Cup Final 2026: Kick-Off Times and How to Watch Kangaroos v New Zealand
 Lifestyle7 Signs Your Social Battery Is Running Low (and Why You Keep Cancelling Plans)
 Lifestyle · Food & HealthThanksgiving Food Safety: How Long Leftovers Last and the Safe Turkey Temperature
 Lifestyle7 Quiet Habits of Emotionally Intelligent People, According to Psychologists
 LifestylePeople Who Don’t Like Celebrating Their Birthday Often Share These 7 Traits