Canada CCUS Tax Credit: 60% Rates and Supply Chain Rules
Canada's refundable CCUS Investment Tax Credit reimburses 60% of eligible Direct Air Capture capex, 50% of industrial capture, and 37.5% of transport and storage equipment through 2035, subject to prevailing wage compliance and NRCan technical review.
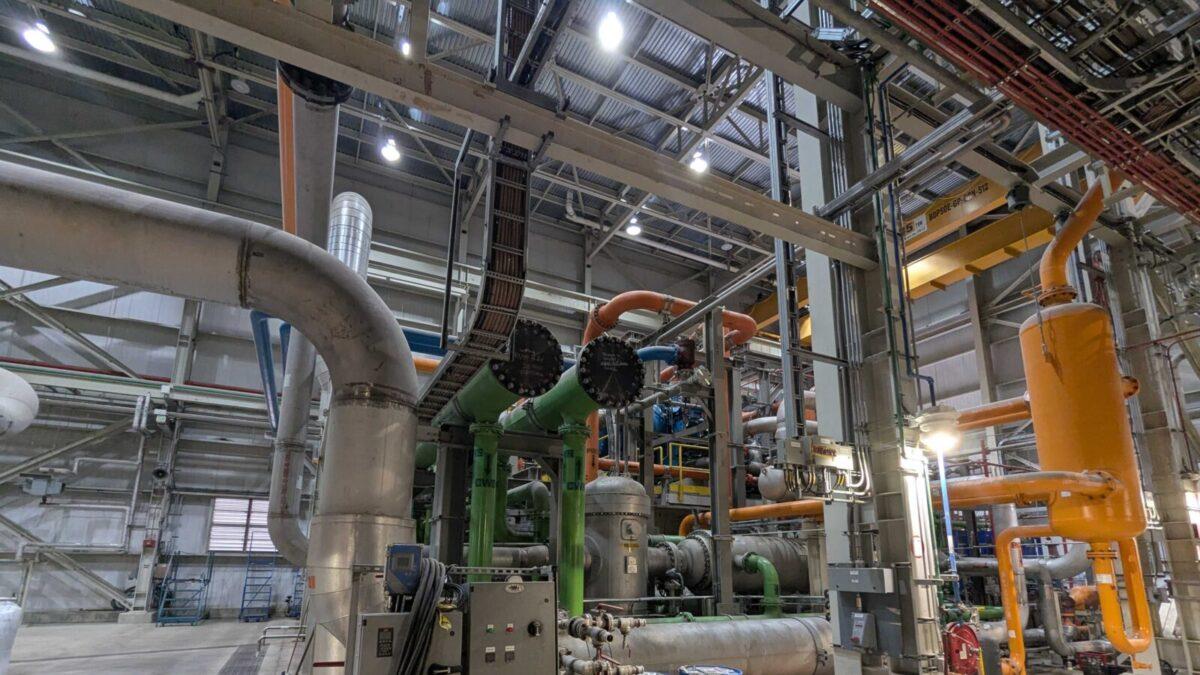
Canada's refundable carbon capture and storage Investment Tax Credit (CCUS ITC) covers up to 60% of qualified Direct Air Capture capital expenditures, 50% for industrial point-source capture, and 37.5% for CO2 transportation, storage, and utilization equipment through December 31, 2035. Industrial sponsors must secure technical project validation from Natural Resources Canada (NRCan) and meet federal labour standards to avoid a 10-percentage-point credit reduction.
- Headline Refundable Rates (2022–2035): 60% for Direct Air Capture (DAC), 50% for other eligible capture equipment, and 37.5% for CO2 transport, storage, and concrete mineralization.
- Post-2035 Step-Down: From 2036 through 2040, credit rates drop by half to 30%, 25%, and 18.75% before expiring.
- Labour Penalty: Failing to elect and satisfy federal prevailing wage and apprenticeship requirements cuts the applicable ITC rate by 10 percentage points.
- Dual Agency Oversight: NRCan validates engineering plans and annual CO2 storage compliance, while the Canada Revenue Agency (CRA) processes tax filings and 20-year permanence audits.
CCUS ITC Rate Tiers and Capital Cost Allowances
Administered jointly by the Canada Revenue Agency (CRA) and Natural Resources Canada (NRCan), the CCUS ITC is refundable, meaning project developers with limited current-year Canadian corporate income tax liability still receive direct cash payouts. Eligible assets map to dedicated Capital Cost Allowance (CCA) classes, primarily Class 57 (8% declining balance for capture, transport, and storage equipment) and Class 58 (20% for monitoring and dedicated geological verification equipment).
| Asset Category | Full Rate (2022–2035) | Reduced Rate (Non-Labour) | Phase-Out Rate (2036–2040) |
|---|---|---|---|
| Direct Air Capture (DAC) Equipment | 60.0% | 50.0% | 30.0% (20.0% without labour) |
| Point-Source Industrial Capture | 50.0% | 40.0% | 25.0% (15.0% without labour) |
| CO2 Transportation & Pipeline Systems | 37.5% | 27.5% | 18.75% (8.75% without labour) |
| Geological Storage & Concrete Use | 37.5% | 27.5% | 18.75% (8.75% without labour) |
As documented in the IEA CCUS policy record, enhanced oil recovery (EOR) is explicitly excluded from eligible uses under Canada's federal CCUS ITC, concentrating capital on dedicated saline aquifer sequestration and permanent industrial mineralization. Because the credit targets upfront capital expenditure rather than per-ton production subsidies, it substantially lowers initial debt financing requirements for heavy industry.
Infrastructure developers coordinating Alberta and Saskatchewan sequestration corridors face similar permitting and power-grid constraints seen in Canada critical minerals infrastructure bottlenecks.
Engineering Supply Chain, Labour Rules, and Storage Governance
Claiming the full 60%, 50%, or 37.5% rate requires upfront project plan submission to NRCan covering Front-End Engineering Design (FEED), amine scrubbing or cryogenic capture specifications, pipeline compression sizing, and verified storage basin capacity. Under CRA compliance rules, projects remain subject to knowledge-sharing reporting and 20-year storage permanence reviews; if captured CO2 shifts from eligible sequestration to ineligible uses within the recovery window, tax credit clawbacks apply.
Equipment procurement teams also face strict domestic labour verification: contractors supplying field fabrication, compression skids, and pipeline installation must document prevailing regional union-equivalent wages and at least 10% Red Seal apprentice hours across designated trades, or forfeit 10 percentage points of refundable capex support. Dual-use power and steam equipment must also be apportioned carefully so only the fraction supporting carbon capture enters the eligible expenditure base.
For comparison with European industrial decarbonization models, see our review of UK carbon capture cluster rules and transport-and-storage regulatory frameworks.
Industrial Decarbonization Economics and Carbon Contracts
Beyond tax credits, commercial viability for Canadian industrial emitters depends on stacking federal CCUS ITC capital recovery with provincial carbon pricing compliance under Alberta's Technology Innovation and Emissions Reduction (TIER) system and federal Output-Based Pricing System (OBPS) benchmarks. When facilities capture and permanently store CO2 rather than paying escalating industrial carbon levies, avoided compliance costs combine with tradeable emission performance credits to stabilize long-term operating cash flows.
The Canada Growth Fund and provincial royalty or grant frameworks also provide bespoke carbon contracts for difference (CCfDs) that underwrite future carbon-credit floor prices for large-scale capture hubs. Under Alberta's Alberta Carbon Capture Incentive Program (ACCIP) and federal clean-economy incentives, industrial sponsors layer capital grants with refundable tax credits to lower project debt service ratios. For engineering and finance leaders evaluating amine scrubbing equipment, high-pressure compression skids, and multi-user trunkline tariffs, locking predictable offtake or policy floor pricing before Final Investment Decision (FID) prevents margin compression if industrial benchmark prices fluctuate over a 15-to-20-year asset life.
Strategic Implications for Energy and Industrial Buyers
Canadian oil sands, petrochemical, cement, and clean hydrogen operators evaluating commercial capture systems should lock FEED studies and NRCan project submissions well ahead of the 2035 full-rate cutoff. Sponsors building multi-emitter CO2 trunklines must structure EPC contracts with explicit prevailing-wage and apprenticeship audit clauses to protect the 37.5% transport and storage credit, because a 10-percentage-point penalty on a C$500 million pipeline equals C$50 million in lost refundable cash.
For cross-border energy groups comparing North American sites, Canada's upfront refundable capex structure pairs naturally with long-term carbon contracts for difference, whereas US facilities rely on per-ton production credits over 12 years. Engineering procurement teams should also audit Class 57 and Class 58 Capital Cost Allowance depreciation schedules alongside provincial sales tax rules in Alberta, Saskatchewan, and Ontario before issuing major purchase orders. Securing NRCan technical sign-off before major equipment procurement ensures capex schedules, ESG reporting software, and tax equity structures remain aligned through commissioning.
 Take the quizWhat Kind of Holiday Spender Are You? Take the Black Friday QuizStart →





 Lifestyle · Food & HealthNormal Blood Pressure Chart by Age: Healthy Ranges Explained
 Lifestyle · Food & HealthWhat Is Raynaud’s Syndrome? Why Fingers Turn White in the Cold
 Lifestyle · Food & Health4 Ways Walking After Meals Helps Your Body, Doctors Say
 Lifestyle · Food & Health4 Reasons to Eat Oatmeal, According to Nutrition Experts